Sole traders used to dealing with their tax records once a year will need to adjust to a much more regular reporting routine. Making Tax Digital for Income Tax replaces the traditional annual approach with digital record keeping and quarterly updates to HMRC, changing how qualifying sole traders manage their tax obligations throughout the year.
For anyone who has relied on a folder of receipts and a spreadsheet at year end, the adjustment is significant. The rules are introduced in stages based on qualifying income, the software requirements are specific, and the penalty system works differently from the previous approach. Knowing where you sit in the timetable and what HMRC expects once MTD applies is the starting point.
How to Get Ready for MTD as a Sole Trader
Here are the points sole traders should understand before moving to Making Tax Digital:
1. Check If and When the Rules Apply to You
The first wave started on 6 April 2026 for sole traders and landlords with qualifying income above £50,000. April 2027 brings in anyone above £30,000, and April 2028 extends it to those above £20,000. Qualifying income is gross income before expenses, not taxable profit, and self-employment and property income are added together.
A trade turning over £34,000 alongside £18,000 of rent crosses the threshold even though neither source reaches it alone. HMRC uses an earlier return to set your entry point, so figures from two years back can decide your start date. Business advisory support is worth taking early if your income sits near a band.
2. Move Your Record Keeping Into Compatible Software
Every business transaction has to be recorded digitally, with the date, amount and category held in software that can talk to HMRC. Paper cashbooks no longer satisfy the requirement, and a standalone spreadsheet only works when bridging software carries the figures across. Check any package against HMRC’s published list of compatible products before committing.
Sole traders with staff should confirm the same system handles payroll services, since running two disconnected tools creates duplicate work every month. Bank feeds and receipt capture save real time once quarterly reporting begins, so test them on your own transactions. Switching at the start of a tax year is easier than moving mid-year.
3. Get Used to the Quarterly Update Cycle
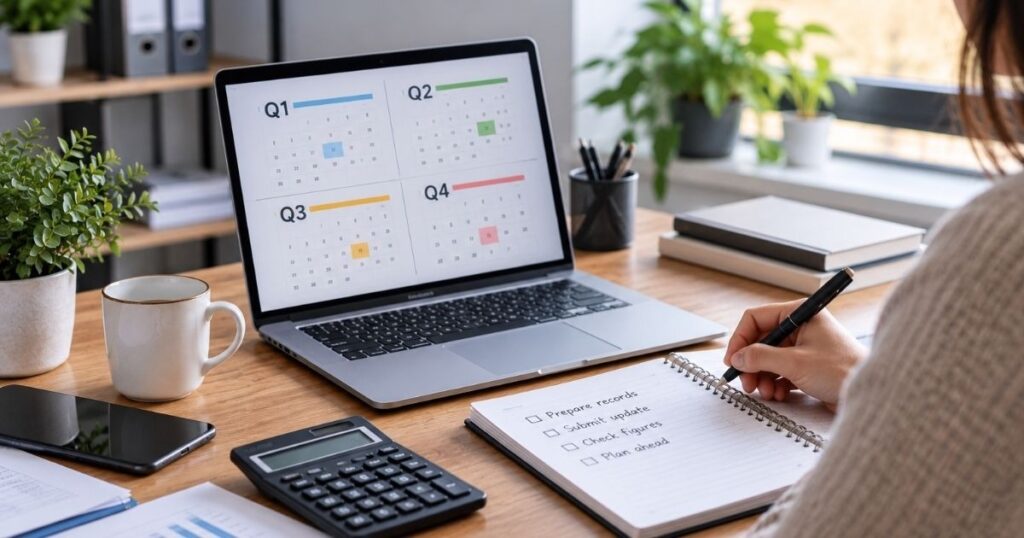
Four updates are due each tax year, covering the quarters ending 5 July, 5 October, 5 January and 5 April, with deadlines on the 7th of the following month. An election to use calendar quarters is available and suits anyone whose bookkeeping already runs to month end.
Updates are cumulative totals of income and expenses for the year to date, so an error picked up later gets corrected in the next submission. Nothing here carries the scrutiny of audit services, as HMRC does not review the figures line by line at this stage. No tax payment falls due alongside them and no accounting adjustments are needed.
4. Know What Replaces the Annual Return
A final declaration takes the place of the self assessment return and is due by 31 January after the tax year ends. This is where capital allowances, private use adjustments, reliefs and any other income are brought in to produce the full picture and settle the figures for the year. Payment dates are unchanged.
The balancing payment still falls on 31 January, with payments on account on 31 January and 31 July. Quarterly reporting changes the rhythm of the paperwork without moving the tax bill forward, though seeing your position four times a year makes budgeting for the January payment easier than working from one annual set of numbers.
5. Understand How the Penalty System Works
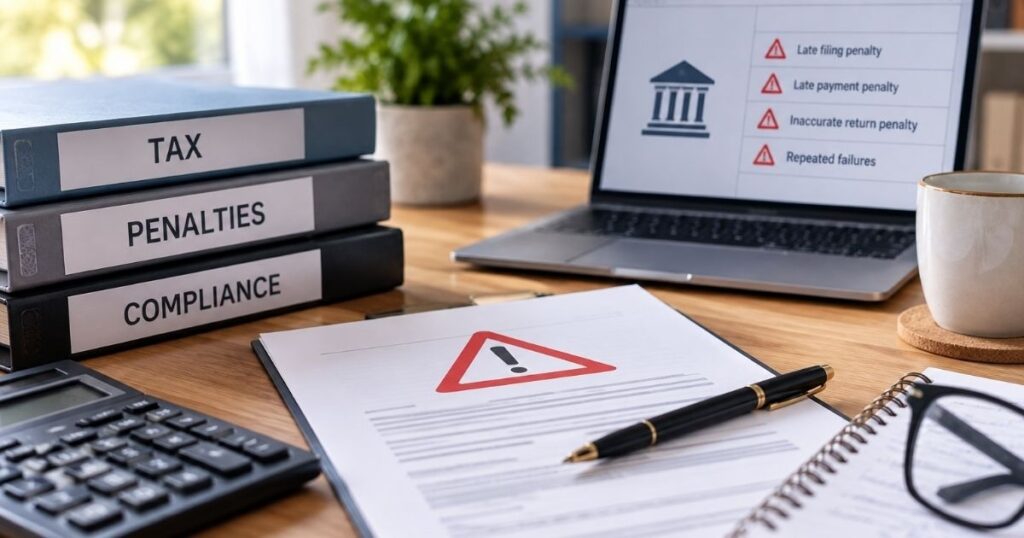
Late submissions attract points instead of an immediate fine. A point is issued for each missed deadline, and reaching the threshold triggers a £200 penalty, with further penalties for each later failure until the points expire through a period of compliance. Late payment penalties are charged separately and escalate the longer a balance sits unpaid, starting at 15 days overdue and increasing again at 30 days.
Interest runs alongside them, so early contact with HMRC is worth making when cash flow is tight. Time to pay arrangements remain available and stop further penalties building once a plan is agreed with HMRC and the instalments are kept to.
Where Sole Traders Get Caught Out
The rules themselves are manageable. The problems tend to come from habits built up under the old annual system that no longer hold once reporting runs four times a year.
- Treating the quarterly figure as a tax demand. Updates are informational and no payment is triggered by them.
- Mixing personal and business spending in one account. Categorising a shared account every quarter takes far longer than separating the two at the outset.
- Judging eligibility on profit. The test looks at gross income across every trade and property, so low-margin businesses are pulled in sooner than owners expect.
- Leaving software selection late. A last-minute migration means opening balances and historic transactions get entered under time pressure, and errors carried in at that point follow you through the year.
Most of these problems are easier to avoid when the right processes are in place before MTD applies. Separating business transactions, choosing compatible software early and understanding what each submission requires can make quarterly reporting much easier to manage once the new routine begins.
Preparing Before Your Start Date Arrives
The businesses that cope well with MTD are the ones that move their bookkeeping across early and treat the first few quarters as a trial run. Leaving software selection until the month before your start date leaves little room to identify data problems, learn the system or correct gaps in existing records.
Getting digital records in place early, deciding who will prepare each submission and running a full quarter in advance can make the transition much smoother. It also gives you time to test bank feeds, categorise transactions correctly and establish a routine, turning MTD from a compliance obligation into a clearer way to track trading throughout the year.